Numbers uncomplicated, suits unnecessary

Remote accountant for growing UK businesses

Numbers uncomplicated, suits unnecessary

Remote accountant for growing UK businesses

Clear finances, down-to-earth results

Clear finances, down-to-earth results

Say goodbye to stuffy suits and jargon-filled conversations you can't understand. I offer financial solutions in a refreshingly straightforward approach, for people who want to reach their business goals faster and achieve financial security without the accounting headache.

Free up your time, enjoy your life

I know your business is important to you. But so is your life outside of work. Let me take care of your numbers so you can be there for life’s more important moments.

Free up your time, enjoy your life

My mission is to help you create a roadmap for financial success, set achievable goals and help guide you towards them.

⁠— Pat van Aalst

Popular services

I offer a range of accounting services to help your business flourish.

Virtual Finance Manager

Leave me to manage your finance function so you can concentrate on the day-to-day running of your business.

Bookkeeping

Stay on top of your numbers with a bookkeeping solution that gives you meticulously accurate financial records.

Management Accounts

Make informed business decisions and keep your business finances under control with my management accounts service.

Corporation Tax

Meet your tax obligations with an expert solution, ensuring compliance and maximising savings for your business.

Payroll

I offer an effortless payroll solution, ensuring accurate and timely payments for your team every single time.

VAT

Simplifying this complex process by preparing and filing your VAT returns with HMRC on your behalf.

Why choose us?

Here's just a few reasons why people choose to work with me.

Remote accounting

I support clients across the UK with expert accounting services delivered online – no travel, no office visits, just straightforward help when you need it.

Year-round support

Unlike some accountants who only seem to appear at tax time, I'm here for you throughout the year to help keep your business on track.

Message Received Payroll Completed Pat van Aalst January £977.50 10 January Payroll Completed HMRC have emailed - help! Message sent

Tailored solutions

My services are never one-size-fits-all. I take the time to understand your specific needs and create solutions that align with your goals.

Pat standing behind a YouTube video player of Pat van Aalst

Welcome to stress-free accounting

From my initial consultation, all the way through to when I start work, my seamless process ensures that you can focus on what matters, helping you leave the stress of finances behind.

Latest articles

By Pat van Aalst • October 29, 2026
Autumn Budget 2026: What does it mean for you and your business? Chancellor John Healey delivered his first Budget on 28 October 2026, promising to give households and businesses some much-needed 'breathing space' from rising costs. While the headline rates of Income Tax on earnings, National Insurance and VAT remain unchanged, several announcements could have significant implications over the coming years. The Government expects its tax measures to raise around £7 billion a year by 2031/32, with many changes taking effect from April 2027. Here's what you need to know. Income Tax and allowances The Personal Allowance remains frozen at £12,570 for 2027/28, with most Income Tax and National Insurance thresholds unchanged until 2030/31. As earnings increase, more income may therefore become subject to tax. From 6 April 2027, Income Tax rates on savings and personal rental income will increase by four percentage points to 24%, 44% and 49%. Meanwhile, the Trading Allowance and Self Assessment trading income reporting threshold will increase from £1,000 to £3,000. Changes affecting businesses and employers The National Living Wage will rise by 3.9% to £13.21 per hour from 1 April 2027. Employers should also account for associated National Insurance and pension costs when reviewing their budgets. From 6 April 2027, Income Tax on company cars, vans, fuel and medical benefits will be collected through payroll, with most other taxable benefits following in April 2028. For businesses investing in equipment, the Annual Investment Allowance remains at £1 million. However, the main Writing Down Allowance will fall from 14% to 12% in April 2027, while the relevant First Year Allowance increases from 40% to 50% from January 2027. Corporation Tax rates remain unchanged at 19% for small profits and 25% at the main rate. Business mileage: motorcycles miss out again There is some welcome news for those using their own cars or vans for business. The 55p allowance for the first 10,000 business miles is being made permanent, while the rate for additional miles increases from 25p to 35p from April 2027. Unfortunately, the motorcycle mileage allowance remains at 24p per mile. Having previously supported the Motorcycle Action Group's campaign to increase this to 45p, I'm disappointed that motorcycles have once again been overlooked. As both a motorcyclist and an accountant, I believe there's a strong case for reviewing an allowance that hasn't changed since 2002. You can read more about my support for the campaign in my earlier article . Company directors and business owners From 6 April 2027, the lifetime limit for Business Asset Disposal Relief will fall from £1 million to £500,000, although the reduced Capital Gains Tax rate remains at 18%. Anyone considering selling their business should review the potential implications before committing to a transaction. The Government is also reviewing how profits are extracted from companies, with reforms expected from April 2028. Corporation Tax rates themselves remain unchanged. Qualifying retail, hospitality and leisure businesses in England will also benefit from changes to Business Rates Relief from April 2027, including full Small Business Rates Relief for eligible properties with a rateable value of up to £18,000. Making Tax Digital and electronic invoicing From April 2027, Making Tax Digital for Income Tax will generally apply to sole traders and landlords whose combined qualifying gross trading and property income exceeded £30,000 in 2025/26. Those affected will need to maintain digital records and submit quarterly updates to HMRC. From April 2029, VAT-registered businesses will also be required to issue and receive structured electronic VAT invoices, unless exempt. Simply sending PDF invoices won't meet the new requirements, making suitable accounting software increasingly important. Savings, pensions and household costs The planned reduction to the cash ISA limit has been reversed, meaning adults can continue saving up to £20,000 annually in cash ISAs. From April 2027, most unused pension funds and pension death benefits will be included in estates for Inheritance Tax purposes, potentially affecting estate planning. On household costs, the temporary 0% VAT rate on domestic electricity will continue until 30 June 2027, while eligible households in England will receive a £100 Household Energy Payment from January 2027. What should you do now? This Budget contained plenty of smaller announcements rather than one or two headline-grabbing changes. Some provide welcome relief, while others could increase costs or create additional administrative responsibilities. Although several measures still require legislation or further guidance, there's already plenty worth considering, particularly for employers, landlords and business owners planning future investments or a sale. The important thing isn't reacting to every Budget headline, but understanding which changes affect your circumstances and planning accordingly. If you're unsure what the Budget means for you or your business, please get in touch . We can help you understand the changes and plan ahead.
By Pat van Aalst • October 24, 2026
HMRC cancels record number of tax penalties – could yours be challenged? HMRC cancelled a record 48,189 tax penalties during the 2025/26 tax year, with new figures suggesting that challenging a penalty can be worthwhile if you believe it's been issued incorrectly. According to recent analysis, 65% of penalties challenged by taxpayers were cancelled. Most related to automatic fines for late filing or late payment, including the familiar £100 penalty for missing the Self Assessment deadline. Why are so many penalties being overturned? The number of cancelled penalties has been rising. The 48,189 cancelled in 2025/26 represents a 4% increase on the 46,266 overturned in 2024/25, and a reported 75% increase since 2020/21, when 5,499 penalties were cancelled during the pandemic. Many of these penalties are generated automatically, meaning there isn't necessarily someone reviewing the individual circumstances before a fine is issued. That doesn't mean every penalty is wrong, of course, but it does mean there can be circumstances that haven't been properly considered. Separate figures covering HMRC's statutory reviews, which deal with more complex tax disputes, also show an increase in decisions being changed. HMRC cancelled or amended 926 substantive decisions in 2025/26, up 35% from 688 the previous year. Meanwhile, the proportion of reviews that upheld HMRC's original decision fell from 73% to 67%. When might a penalty be challenged? One case highlighted by accountancy firm Price Bailey involved a taxpayer who received £1,600 in automated late filing penalties. The taxpayer believed their return had been successfully submitted after HMRC's online system appeared to indicate that the filing was complete. Subsequent emails from HMRC were diverted into a junk folder, meaning the problem wasn't identified until the penalties had accumulated. The case eventually reached a tax tribunal, which overturned the penalties, finding that easily missed automated communications did not amount to effective notice in those circumstances. It's a useful reminder that an automatically generated penalty isn't necessarily the final word, particularly where there are questions about whether HMRC's systems or communications have contributed to the problem. Does this mean HMRC is getting it wrong? Not necessarily in every case, but the figures do highlight the importance of reviewing penalties rather than simply assuming they're correct. Andrew Park, tax investigations partner at Price Bailey, pointed out that high-volume automated penalties lack human oversight when they're first issued. He explained that HMRC's independent internal reviewers provide an important additional check, allowing individual circumstances to be considered before disputes potentially reach a tribunal. Of course, the fact that 65% of challenged penalties were cancelled doesn't mean that 65% of all penalties issued by HMRC are incorrect. It tells us about the cases taxpayers chose to challenge, rather than every penalty HMRC issued. What should you do if you receive a penalty? The first thing is not to ignore it. Check what the penalty relates to, whether the information HMRC has used is correct and whether there are circumstances that might justify an appeal. There are time limits for challenging penalties, so it's important to act promptly rather than leaving the letter sitting on your desk. Equally, it's worth remembering that a genuine missed deadline doesn't automatically mean a penalty will be cancelled. HMRC will consider the circumstances, and an appeal needs to have a reasonable basis. For me, the interesting point from these figures is that HMRC's original decision isn't always the end of the matter. Automated systems are useful for handling large volumes of work, but they don't necessarily capture every individual circumstance. If you've received an HMRC penalty and aren't sure whether it's correct, get in touch. We can look at the circumstances and help you understand whether there may be grounds to challenge it.
By Pat van Aalst • October 23, 2026
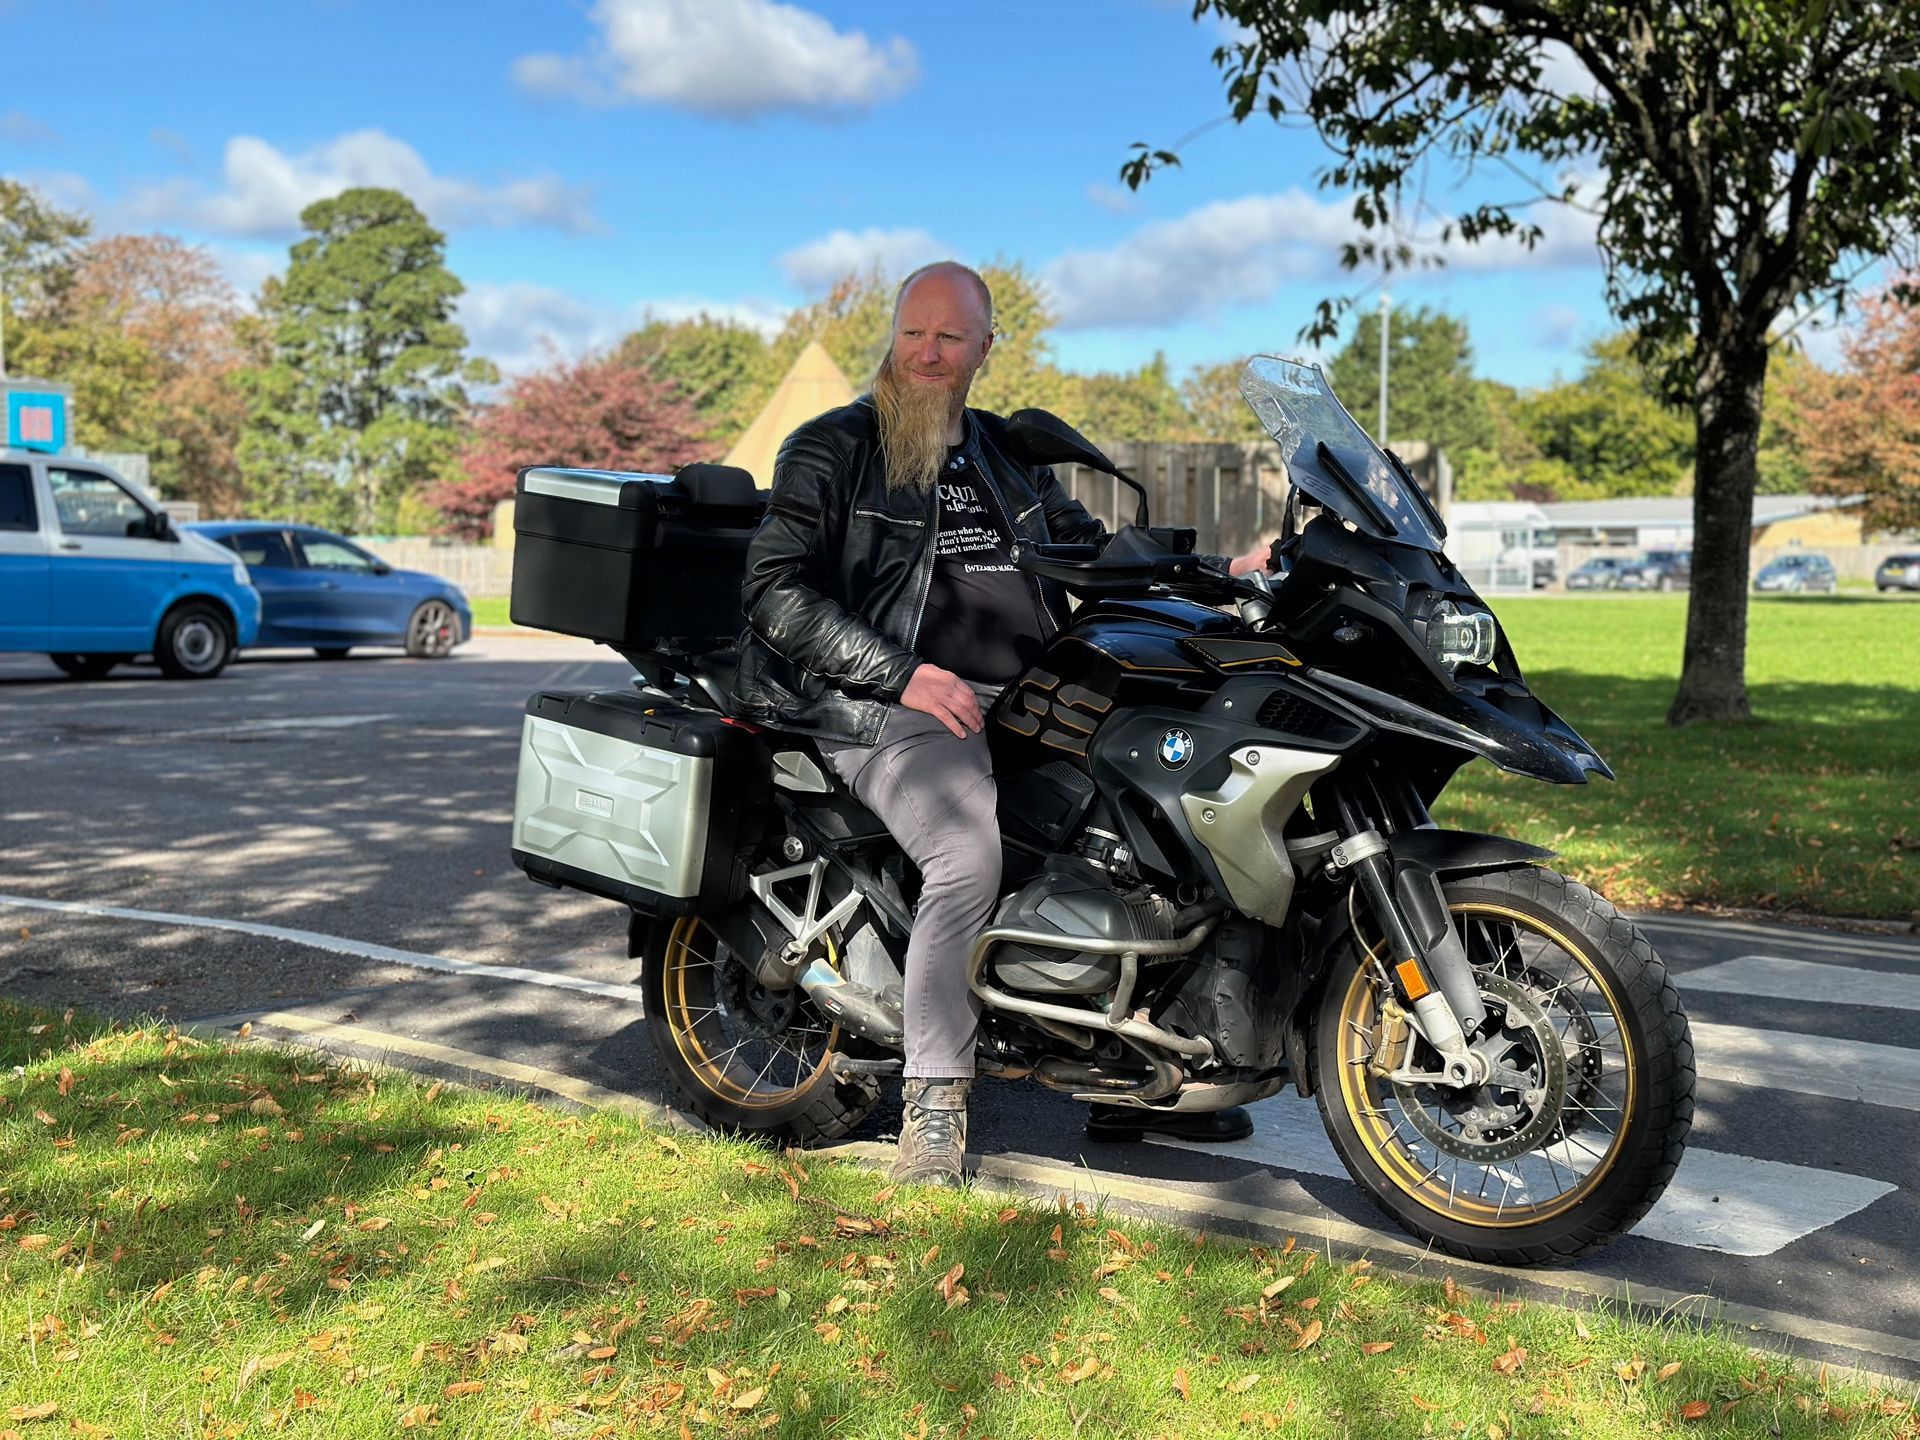
I'm a motorcyclist and an accountant, so the Motorcycle Action Group's (MAG) campaign to increase the approved motorcycle mileage allowance caught my attention from two directions. The allowance has been 24p per mile since April 2002. That's nearly a quarter of a century without an increase, despite everything that's happened to the cost of fuel, servicing, insurance and generally keeping a vehicle on the road. Meanwhile, the approved rate for cars and vans increased from 45p to 55p for the first 10,000 business miles earlier this year. The motorcycle rate stayed exactly where it was. Now, I don't think motorcycles and cars should necessarily attract the same mileage allowance. They have different running costs, and it's reasonable for the tax system to recognise that. But there's a difference between recognising those differences and leaving one rate untouched for 24 years while another is reviewed and increased. MAG is asking the Treasury to increase the motorcycle allowance to 45p per mile in the Autumn Budget on 28 October. Having looked at its arguments, I think MAG has made a reasonable case for the increase, and it's a campaign I'm happy to support. I should probably declare my interest here. I use my motorcycle for some business journeys in my accountancy practice, so I benefit from the mileage rules myself. But I don't cover particularly high business mileage, and the financial difference to me personally would be fairly modest. My interest is more in whether the system makes sense and treats different forms of transport consistently. There's also a distinction worth making between a mileage allowance and the amount of money somebody actually receives. An employer can reimburse an employee for qualifying business mileage at HMRC's approved rate without that payment normally being subject to tax. Where an employer pays less, the employee may be able to claim tax relief on the difference, which isn't quite the same as receiving the missing mileage allowance. For a self-employed person using the simplified mileage method, the allowance reduces taxable profit rather than providing a reimbursement. So an increase from 24p to 45p wouldn't automatically put another 21p per mile into everybody's pocket. What I particularly like about MAG's campaign is that it hasn't simply demanded the same rate as cars. Instead, MAG has put together research and modelling to support its proposal, including estimates of how much the change might cost the Treasury. Its modelling suggests that increasing the rate to 45p could cost the Treasury no more than £34 million a year, even under its higher-cost scenario. That's MAG's estimate, rather than an independently verified Treasury costing, but at least it gives us something specific to examine and challenge. And I think that's a worthwhile approach. If we're going to argue that an allowance is unfair, we should be prepared to explain what a fairer allowance might look like and what changing it could cost. There's another aspect of the policy that interests me. We tend to think of mileage rates as if somebody at the Treasury has worked out the average cost of running each type of vehicle and arrived at a carefully calculated figure. In reality, the Treasury considers a range of factors when setting these rates, rather than applying one fixed cost formula. That seems entirely reasonable. Different vehicles have different costs, and there are wider questions about what forms of transport the government wants to encourage. Motorcycles generally occupy less road space than cars, particularly when parked, and can offer advantages in congested areas. They're not without environmental or other drawbacks, and I certainly wouldn't suggest that every motorcycle is especially economical to run. A large touring motorcycle and a small commuter bike are rather different propositions. But if wider policy considerations form part of the decision, it seems reasonable to ask whether motorcycles' potential contribution to reducing congestion and demand for road space is being given appropriate consideration. There's an interesting comparison with bicycles, too. Their approved mileage rate is 20p, just 4p less than motorcycles. I'm certainly not suggesting that the bicycle allowance should be reduced, and encouraging cycling is a perfectly legitimate policy objective. But it does raise the question of whether we're applying a consistent approach to different forms of transport, particularly if these allowances reflect wider policy considerations as well as running costs. Ultimately, I'd like to see mileage allowances based on current evidence, with a clear explanation of the reasoning behind them. If that produces different rates for different vehicles, fine. What is harder to justify is a motorcycle rate that hasn't changed since 2002, particularly when the car rate has recently been increased. MAG has made its submission to the Treasury, and the decision now rests with the government. Whether the Chancellor accepts the proposed 45p rate remains to be seen. I hope the campaign succeeds. Not because I expect to make a fortune from claiming a few extra pence on my own business journeys, but because I think there's a good case for reviewing an allowance that has been overlooked for far too long. You can read MAG's campaign and the reasoning behind its proposal here: https://mag-uk.org/a-pay-rise-for-motorcyclists-its-down-to-the-budget-now/ With the Budget due on 28 October, we shouldn't have too long to wait to see whether the Treasury agrees.
Read More Articles ⟶

Experience accounting without the headache

Book a call with me today for a refreshing approach to financial management. No suits, no jargon, just practical accounting solutions that make a difference.

Get in touch ⟶

Experience accounting without the headache

Book a call with me today for a refreshing approach to financial management. No suits, no jargon, just practical accounting solutions that make a difference.

Get in touch ⟶

Experience accounting without the headache

Book a call with me today for a refreshing approach to financial management.  No matter where in the UK your business is based, you'll get practical accounting solutions that make a real difference.

Contact Us ⟶